For most of 2026 the sector has been planning on headlines. "Budgets are being cut." "The big four are closing." "Demand is moving to Europe." Each of those is partly true, and each is too blunt to build a 2027 recruitment plan on.
Over the past two months the primary sources have caught up. The Institute of International Education published Open Doors 2025 and the Fall 2025 Snapshot, a survey of 825 US institutions. Immigration, Refugees and Citizenship Canada briefed Parliament, published the 2026 allocations and released its transition binder. The UK Home Office closed its year to June 2026. Read together, they say something more precise than the headlines, and in places the opposite of them.
First, the Numbers You Already Feel
If your office lost colleagues this year, none of this is news. It is worth putting on one page anyway, because the same figures are the ones a finance committee will use, and the plan that survives is the one that starts from them rather than from the brochure.
| Where | What happened in 2025/26 | Source |
|---|---|---|
| United States, visas | F-1 visas issued in 2025 fell by roughly a quarter to a third on 2024. Summer issuances, the ones that feed the fall intake, fell 36%. Refusal rates reached 61% for India and 64% for Africa. | State Department issuance data via ICEF Monitor and Inside Higher Ed |
| United States, enrolment | New international enrolment down 17% in fall 2025, costing about US$1.1 billion and 23,000 jobs. Active F-1 and M-1 records fell from 1,234,288 in February to 1,188,918 in May 2026. For fall 2026, 63% of institutions expect a further decline, 59% received fewer applications, and NAFSA projects up to 111,000 fewer students, US$3.4 billion and nearly 40,000 jobs. | IIE Fall 2025 and Spring 2026 Snapshots; SEVIS via the Presidents' Alliance; NAFSA |
| Canada | Study permit holders down from 928,430 to 691,215 in a year, new students down 61%. Ontario's colleges alone report C$1.8 billion in lost revenue, more than 600 programmes suspended or cancelled and around 8,000 jobs eliminated, with the union's count near 10,000. | IRCC; Colleges Ontario and OPSEU via CBC News |
| United Kingdom | Sponsored study visas down 41% from the 2023 peak. Universities shed about 13,300 jobs in 2024/25, and the union's tracker lists 108 institutions in redundancy or restructuring with more than 15,000 cuts announced. | Home Office; UCU tracker via The PIE News |
| Australia | Almost 4,000 university jobs cut in 2025 and hundreds more in 2026, with offshore higher-education refusals at 32.5% and a fixed national planning level. | NTEU and ABC News; Department of Home Affairs |
| Sector budgets | More than four in ten institutions in Australia, Canada, the UK and New Zealand plan budget cuts in the next twelve months. Spend expectations for recruitment staff fell from 61% of institutions to 17% in three years. | Global Survey of International Education Leaders (Navitas, Nous, The PIE) |
Two things are true at once. Fewer recruiters are travelling on fewer budgets, while visa restrictions and changing policies are reducing the number of places available to international students. But the flow that remains is being redirected rather than switched off. The rest of this article is about the second half, because the first half is already in your inbox.
Recruitment Budgets Did Not Collapse. They Moved.
The most repeated number of the year comes from the Global Survey of International Education Leaders run by Navitas, Nous and The PIE News: more than four in ten universities in Australia, Canada, the United Kingdom and New Zealand plan budget cuts in the next twelve months. It is a real number. It is also a number about four countries, and it is routinely quoted as if it covered the sector.
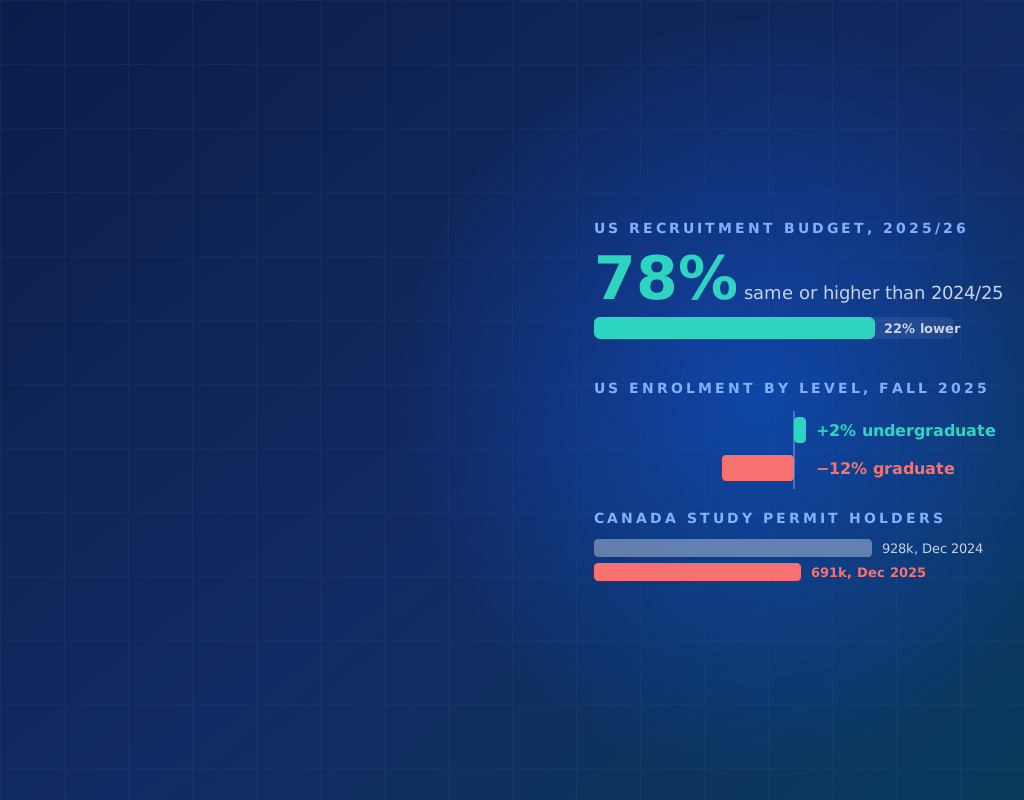
The United States, the largest destination by a distance, reports something different. In the IIE Fall 2025 Snapshot, 84% of institutions say international recruitment remains a priority, and 78% say financial support for it is the same or higher than the year before. Among institutions that grew new enrolment, 71% credit active recruitment initiatives and 54% credit outreach to admitted students.
The more useful signal is inside the cuts, not their size. In the same GISEL survey, the share of universities expecting to spend more on digital platforms and aggregators fell from 54% in 2022 to 22%. The share expecting to spend more on marketing and recruitment staff fell from 61% to 17%. What survived was not a channel but a test: does this line produce a student the institution can name? Commission agents pass that test, which is why their budgets held. So does a counsellor who places students year after year, a fair where the admissions team meets the family, and a verification step that stops a qualified applicant from becoming a refusal. None of those requires a commission, and the US institutions that grew in 2025 credit active recruitment (71%) and outreach to admitted students (54%), not agent volume.
The budget line that survives a cut is the one that can name the students it produced.
That is the pattern in every dataset this year. Spend is not disappearing. It is migrating from channels that deliver visibility to channels that deliver an attributable enrolment, and it is doing so faster in the countries with caps than in the one without. The one caution is that agent-sourced volume now carries the exposure regulators are targeting: IRCC flagged more than 10,000 fraudulent acceptance letters in 2024, and every cap country has tightened who may be paid and for what. An attributable enrolment that also survives the visa stage is worth more in 2027 than one that merely arrives.
Undergraduate Up, Graduate Down: The US Level Split
Open Doors 2025 records 1,177,766 international students in the United States in 2024/25, a record and a 5% rise. The composition is what matters. Undergraduate enrolment grew 4.2% to 357,231. Graduate enrolment fell 2.7% to 488,481. Optional Practical Training grew 21% to 294,253, the tail of several strong graduate years working its way through.
A note on timing, because it matters for the trend. The 2024/25 record was counted in fall 2024, before the change of administration, and reflects decisions families made in 2022 and 2023. The first year to feel the new visa regime is 2025/26, and it shows: new enrolment down 17% and F-1 issuances down by about a third. Totals fall more slowly than intake because continuing students carry them, which is why 2026/27 is projected down 5% to 10% and why the total is likely to keep declining into 2027 and 2028 as the large earlier cohorts graduate, unless policy reverses. The decline is not evenly spread. It is concentrated at graduate level and in the origins with the highest refusal rates, which is exactly what makes the composition, and not the headline, the planning number.
The Fall 2025 Snapshot shows the same split sharpening. Undergraduate enrolment is up 2%, graduate enrolment is down 12%, OPT up 14%, and new enrolment across all levels down 17%. Fifty-seven percent of institutions report fewer new students; among them, 96% cite visa application concerns and 68% cite travel restrictions. Seventy-two percent are offering deferrals to spring 2026 and 56% to fall 2026, which means a share of this year's loss is a delay rather than a defection.
Two further details from Open Doors belong in any 2027 plan. Families are the primary funder for 51.5% of international students, and the institution itself is the primary funder for 19.3%, ahead of every foreign government combined at 1.7%. The scholarship you publish is the second largest source of money in the system. And 92% of institutions say that without OPT, international students would choose another country. OPT is the American argument against a cheaper European master's, for as long as it lasts.
Growth is also geographically uneven. Texas grew 8.4%, Missouri 11.3%, Illinois 7.0%, Ohio 6.1%. California fell 1.1%. The institutions adding international students are increasingly in the interior and the south.
The Markets American Institutions Say They Are Working
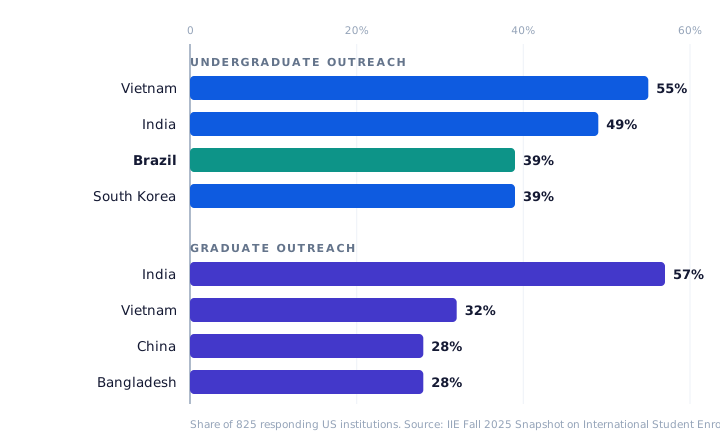
The Snapshot asks institutions which countries they are prioritising for outreach. For undergraduates the answers are Vietnam (55%), India (49%), Brazil (39%) and South Korea (39%). For graduate recruitment they are India (57%), Vietnam (32%), China (28%) and Bangladesh (28%). Latin America appears on the undergraduate list and is absent from the graduate one.
Set that against where the numbers actually moved. Open Doors shows Brazil at 17,277 students (+2.4%), Mexico at 15,652 (+1.2%), Colombia at 10,213 (+0.9%) and Peru at 5,667 (+2.9%), with Colombia and Peru at their largest totals on record. Over the same period, arrivals in August 2025 fell 24% from Asia, 32% from Africa and 17% from the Middle East, and F-1 refusal rates reached 64% for African applicants and 61% for Indian ones.
The reading is not that Latin America is booming. It is that Latin America is holding while the two largest regions are being filtered at the consulate. When an admissions office in the UK can lose its sponsor licence for a refusal rate above 5%, and an American one loses a fifth of its new intake to visa outcomes it does not control, an origin with a low refusal rate stops being a nice-to-have and becomes the scarce asset in the plan.
One more line from the Snapshot deserves attention. Half of US institutions now recruit international undergraduates through US high schools, and a third recruit their own international undergraduates into graduate programmes. The channel institutions trust most is the school and the counsellor who already knows the student. Outside the United States, that channel exists too; it is simply less mapped.
Canada: The Door That Is Open Is the Graduate One
IRCC's own briefing to the parliamentary committee is the clearest statement any government has made this year about what it wants and does not want. The numbers below are the department's.
| What IRCC reports | Figure | What it means for recruitment |
|---|---|---|
| Study permit holders | 928,430 in December 2024 to 691,215 in December 2025 | A quarter of the stock gone in one year, with new arrivals down 61%. |
| New arrivals planned | 155,000 in 2026; 150,000 in 2027 and 2028 | No rebound is budgeted. The 2027 cap is set this autumn with the levels plan. |
| Refusal rate, new permits | 59% January to September 2025, up from 49% | Approval near 58% is expected in 2026 because provincial attestation letters filter applicants first. Pre-qualified applicants clear; volume does not. |
| Master's and doctoral students | Exempt from attestation letters at public institutions from 1 January 2026; about 49,000 permits; doctoral files processed in 14 days; C$1.7 billion over 13 years for research talent | The one segment the government is actively recruiting for. Canadian graduate programmes are a growth product in 2027; colleges and undergraduate volume are not. |
| Proof of funds | C$22,895 from September 2025, C$23,448 from 1 September 2026, indexed annually; financial documentation was the leading refusal reason in June 2026, at 47% of refusals | Financial capacity is now a stated integrity measure, not a formality. |
| Letter-of-acceptance verification | Over 10,000 fraudulent letters flagged in 2024, 4,900 in 2025; penalties for non-compliant institutions from spring 2026 | The institution carries the compliance risk for its pipeline. |
| Post-graduation work permits | Language requirement and in-demand fields; new permits down 20% | "Study, work, stay" is no longer a message that can be made generically. |
| Francophone pilot | 65% approval, against 34% to 39% historically for the same countries | A quietly open lane for French-speaking applicants outside Quebec, and Quebec itself holds the second largest allocation at 93,069. |
Latin America is a small and shrinking source for Canada: Brazil 7,015, Mexico 8,375 and Colombia 6,775 permit holders in 2024, each down between 26% and 35%. The sector's own outlook cites the region for continued growth in language programmes and pathways, which are the segments the cap hits hardest. For Canadian universities, the defensible 2027 pitch to Latin America is a master's or a doctorate at a public institution, with the funds documented.
The Rest of the Map in One Table
| Destination | Official signal | Read for 2027 |
|---|---|---|
| United Kingdom | 383,455 sponsored study visas in the year to June 2026, down 11% on the year and 41% from the 2023 peak. Graduate Route falls to 18 months for applications from 1 January 2027. Levy of £925 per international student from 2028/29. | Still large. Selection by refusal rate and compliance, which favours origins that clear. |
| Australia | National Planning Level held at 295,000 for 2027, no provider allocated fewer places than in 2026. Offshore higher-education refusal reached 32.5% in 2025/26; visa fee A$2,500. | Predictable, and predictability is now an advantage. Managed growth, not expansion. |
| Germany | Around 420,000 international students; three in four universities report stable or rising numbers. Roughly 4% of bachelor's programmes taught in English against about 18% of master's. | A graduate destination for international families. Public universities recruit through DAAD, not through paid presence. |
| France | About 445,000 international students, target 500,000 by 2027. Proof of funds raised to €877.50 a month from 1 August 2026. Differentiated tuition becomes the rule for non-EU students at public universities from September 2026, at €2,895 for a bachelor's and €3,941 for a master's, and 60% of government scholarships go to digital, AI, quantum and biotech. Africa supplies 53% of the total. | Growth by national strategy and by field. Campus France is asking partners for engineering and STEM profiles, not volume. |
| Spain | Over 100,000 international students, an EduBridge fast track, 30 hours of work a week and a 12-month post-study job-search permit. | The natural European home for Spanish-speaking Latin America, mainly for price-sensitive families and for master's. |
| South Korea | 314,397 international students in February 2026, target met two years early. Vietnam 115,131, China 78,529, Uzbekistan 20,609, Mongolia 18,992. | Recruits its own region. Not a competitor for Latin American or African demand. |
| Malaysia | Applications up 26% in two years; China the largest source at 33,216 applications in 2024, then Bangladesh, Indonesia, Pakistan and India, with the Middle East and North Africa fourth by region. | Asian and MENA demand at a lower price point. Same conclusion as Korea. |
| New Zealand | 83,700 international students, target 119,000 by 2034; June 2026 was the strongest month of student visa approvals since 2016. | Small, open and growing, with capacity as the limit. |
The Two Gates Every Destination Now Applies
Put the country tables side by side and a pattern appears that no government states in those words. Every major destination is now screening twice: once on money, once on field or level. The official vocabulary is "sustainable", "managed growth" and "skills needs". The effect is a selection of applicants who can pay and who study what the destination wants.
| Destination | Money gate | Field or level gate |
|---|---|---|
| Canada | C$23,448 in proof of funds from 1 September 2026, indexed every year. Financial documentation is the top refusal reason. | Caps on colleges and undergraduate; master's and doctoral students at public universities exempt; post-graduation work tied to in-demand fields below degree level. |
| United States | No new threshold, but social media vetting, a fixed admission period from 15 September 2026 and refusal rates from 9% (Europe) to 64% (Africa). | Graduate intake falling fastest; undergraduate flat to growing at the largest institutions. |
| United Kingdom | £1,529 a month in London held for 28 days, no dependants for most students. | Graduate Route cut to 18 months from 1 January 2027; the white paper's complaint is graduates outside graduate-level jobs. |
| Australia | A$29,710 for living costs alone, plus a A$2,500 visa fee. | Places allocated per provider; the Genuine Student test accepts a migration pathway for the right graduates. |
| France | €877.50 a month from August 2026 and mandatory non-EU tuition from September 2026. | Strategy aimed at sectors short of skilled workers; 60% of scholarships to priority fields. |
| Netherlands | Standard EU proof of means. | Universities capped foreign intake below 17,000 a year in July 2026; new English-taught programmes only where tied to shortages in STEM, healthcare and technology. |
| Denmark | Standard EU proof of means. | English-taught admissions cut about 10% in 2026, while 800 new English places were created in STEM, IT and maritime studies. |
Two corrections to the intuition that "only the rich get in". The money gate is set at upper-middle class, not wealth. C$23,448 or €877.50 a month excludes the family that was borrowing to go, not the family that already pays private school fees in São Paulo, Bogotá or Mexico City. And the second gate measures field and level, not talent. A strong humanities applicant is outside the French scholarship pool; an average engineering applicant is inside it. The counsellor's job in 2027 is to steer the student toward the field the destination is buying, not only toward the destination.
Quality Has a Definition Now
Every organiser, agent and platform in this industry claims quality over quantity. Until this year the claim could not be checked, so it cost nothing to make. From 2027 the visa officer checks it for you: a lead that fails either gate comes back as a refusal in your own compliance report. That turns quality from a perception into a number, and the number has a definition.
A qualified lead is a student who, for a specific institution, clears four tests:
- Can fund it. Family resources above the proof-of-funds threshold of the destination, declared at registration and verified before the offer.
- Fits what the destination is buying. The right level, and for Canada and continental Europe the right field.
- Is admissible. Grades and language inside the institution's range, visible in the profile before the first conversation.
- Is in the window. An entry date within eighteen months and an action that cost the student something, such as a booked appointment.
Quantity of leads was the old currency. The new one is the share of leads that would survive the visa stage.
The arithmetic follows. A fair that delivers 400 badge scans of which 40 clear both gates costs the same to attend as one that delivers 120 registrants of which 60 clear them, and the second one returns half again as many enrolments for the same flight, the same hotel and the same week of a recruiter's time. Return on a smaller budget comes from the quality of the leads, not their count, and the finance office can see the difference the moment refusals are reported by source.
That share is what to ask of every event, platform and partner before the trip is approved, and what to report afterwards. An event that pre-screens registrants, shows you the profiles in advance, books your appointments with students who have paid to be there, and lets you verify funds before you make an offer is applying the four tests for you. An event that hands you a badge scan list is asking you to apply them at your own expense, after you have flown home.
What This Means for Your 2027 Plan
- Budget by outcome, not by channel. Every survey this year says the same thing: the money that survives is the money that can name the students it produced. Ask each line item for its enrolments, not its impressions.
- Write two plans, one per level. The US is growing at undergraduate and shrinking at graduate. Canada is closed at undergraduate and open at graduate. Continental Europe recruits almost entirely at master's. A single "international" target hides all of that.
- Treat low-refusal origins as a strategic asset. South America's F-1 refusal rate is 22% and Europe's 9%, against 61% for India and 64% for Africa. If your sponsor licence, your yield or your compliance reporting depends on refusal rates, weight your outreach accordingly.
- Requalify the pipeline against both gates before the visa stage. Funds first: Canada at C$23,448, France at €877.50 a month, Australia at A$29,710, the UK at £1,529 a month in London. Then field and level: is this student applying for something the destination is actively admitting? A family that qualified in June may not qualify in September, and the number moved, not the student.
- Work the admitted pool as hard as the prospect pool. Institutions that grew credit outreach to admitted students more than any tactic except active recruitment. With deferrals at 72%, the 2026 admit is the 2027 enrolment.
- Use the counsellor channel outside your home country. Half of US institutions recruit through high schools at home. The same relationship, with a counsellor who knows the student, the grades and the family budget, exists in the origin markets and converts on the same logic.
- Present Canada as a graduate destination and reach Europe through its agencies. The Canadian exemption is explicit. The European public university does not buy presence; DAAD, Campus France, SEPIE and their peers do, and they are buying by field.
- Approve trips on a number, not a brand. Before any event goes in the budget, ask for the refusal rate of the origin, the proof-of-funds threshold of your destination and the share of registrants above it, the number of pre-booked appointments, and the cost per qualified lead. Report the same figures afterwards. It is the only defence a recruitment line has in a budget meeting.
FPP Insight
The headline of 2026 is scarcity, and for the people who lost their jobs this year it is not a headline. The data adds a second word: selection. Governments are not shutting the door so much as narrowing it to the applicants they can fund-check and the fields they want, and institutions are not abandoning recruitment so much as moving it to where they can prove a result.
For a recruitment team, that is better news than the headline, because selection can be planned for and scarcity cannot. The plan has three ingredients the primary sources keep pointing to: the right level for each destination, an origin that clears the consulate, and a way to show the finance office an enrolment rather than a lead. In a year when every trip has to be defended, the return comes from the quality of the leads, and quality now has a definition you can put in the budget request.
We will keep publishing the primary numbers as they land, including the Canadian 2027 cap this autumn, the UK Graduate Route change in January and Open Doors 2026 in November. If the tables behind this article would help your own planning, they are available on request.